The Recruitment Market Is Moving: Are You Positioned Where Growth Is?
Nov 09, 2026The latest evidence from across the UK economy is giving recruitment leaders some encouraging reasons for optimism. Business confidence is improving, the services sector is expanding at its fastest pace for eight months, and services employers are increasing their workforce for the first time in more than two years.
At the same time, substantial investment in aerospace, advanced manufacturing, energy infrastructure and industrial development is creating identifiable opportunities for specialist recruiters.
But the recruitment market is not recovering everywhere at the same pace. Agencies that recognise where growth is emerging will have an advantage over those waiting for a general recovery.
Confidence Is Improving - And Employers Are Starting to Act
October’s Lloyds Business Barometer recorded a six-point increase in business confidence to 47%, comfortably above its long-term average of 30%. Trading expectations and economic optimism also strengthened.
The S&P Global Services PMI reached 52.8 in October, an eight-month high. Crucially, services employment returned to growth for the first time since September 2024. Confidence is a leading indicator, but actual employment growth offers stronger evidence that businesses are beginning to invest in people again.
The latest KPMG/REC Report on Jobs reminds us why we must remain selective. Permanent placements and temporary billings fell in October. Yet the rate of decline in vacancies eased to its slowest in more than two years, with improving permanent demand in IT and computing, engineering, construction and accounting and finance. Opportunities are growing, but they are not evenly distributed.
Follow the Investment - Not Just the Vacancies
The October Budget has provided an even stronger reason to follow the investment. The National Wealth Fund has received an additional £15.4 billion of capital, which its own analysis estimates could create or support around 100,000 jobs by 2035-36. Its expanded priorities include defence, critical minerals, AI and its supply chains, clean energy and strategic industrial sites. Up to £5 billion is earmarked for deployment by the National Wealth Fund and British Business Bank into defence and related security sectors over four years, while £2 billion of the new capital will establish an Energy Wealth Fund. These are projected, longer-term employment impacts - not 100,000 vacancies available today - but they provide recruiters with a valuable map of where future demand could develop.
The Government and Rolls-Royce have announced a £2.5 billion programme to develop next-generation aircraft engines in Britain, supporting thousands of existing jobs and potentially creating significant future employment. Airbus is expanding production at Broughton, with approximately 480 new jobs during 2026.
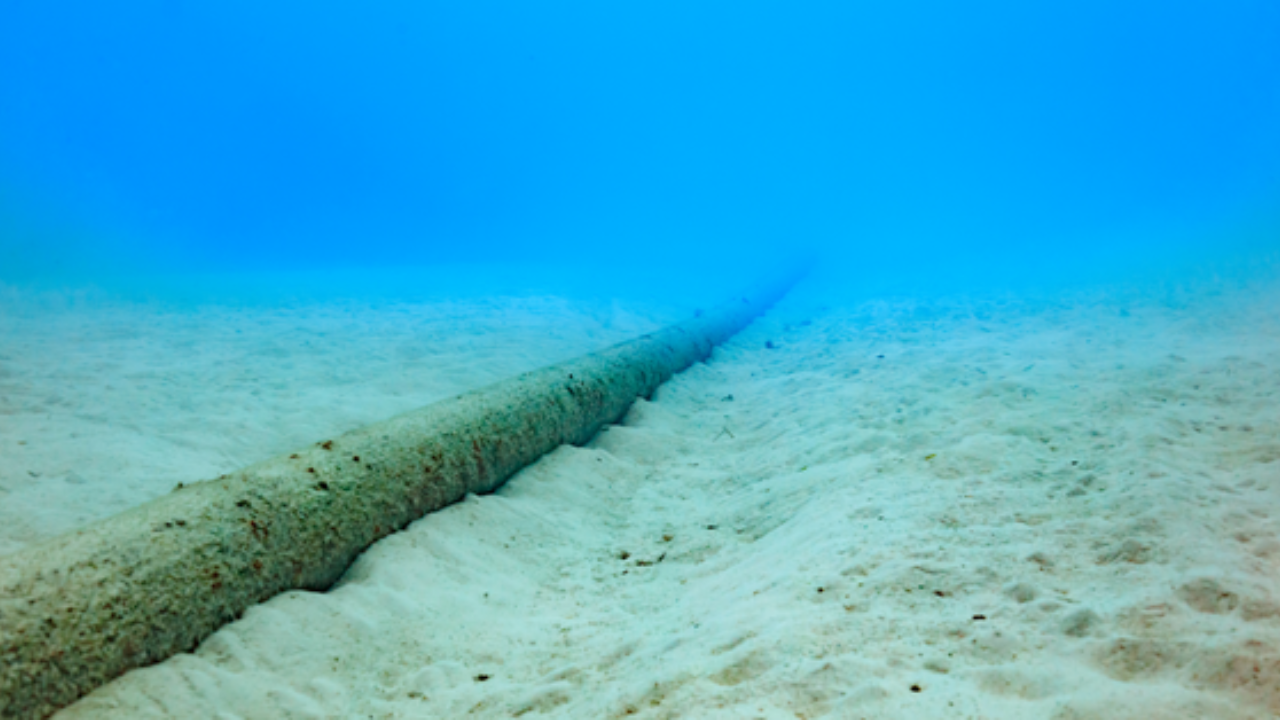
In Scotland, Sumitomo Electric’s new £350 million subsea cable factory is creating 200 jobs and strengthening the supply chain for electricity transmission and offshore energy. The Government’s £700 million Strategic Sites Accelerator aims to unlock industrial developments and attract up to £2 billion in private investment.⁷
The recruitment opportunity extends far beyond the headline employers. Every major investment creates demand through engineering, construction, manufacturing, project management, quality, procurement, logistics, technology and specialist professional services. Understanding these supply chains can reveal opportunities before vacancies are advertised.
The Growth Sectors Are Becoming Easier to Identify
Technology remains important, but the nature of demand is changing. AI is creating opportunities not only for software and data specialists but also across digital infrastructure, energy, engineering and business transformation. Aerospace, electrification and energy infrastructure support advanced manufacturing demand.
Although the Construction PMI remains weak overall, particularly in residential development, data centres, utilities and energy networks are relative bright spots. Construction, technology and engineering are not single markets: each contains specialist niches with very different levels of demand.
The Real Challenge Is Business Development
For much of the past two years, recruitment leaders have understandably focused on protecting margins, retaining good consultants and controlling costs. Those disciplines remain important, but a different challenge is emerging: are consultants equipped to identify and create opportunities rather than simply respond to vacancies?
That means understanding clients’ investment plans, asking better questions about workforce capacity, identifying future skills shortages and building relationships beyond HR and Talent Acquisition. It also means reconsidering where consultants spend their time.
AI must be part of that strategy - not merely to automate administration, but to improve market intelligence, identify growth opportunities, map talent pools and help consultants become more effective commercial advisers. Specialist market knowledge, strong business development and intelligent AI adoption will increasingly distinguish outperforming agencies.
Don’t Wait for the Whole Market to Recover
November’s Greenshoots does not suggest the downturn is over. But confidence has improved, services employment is growing again, specialist vacancy demand is strengthening and substantial investment is creating future recruitment opportunities.
The question is no longer simply “When will recruitment recover?” It is “Where is growth already happening - and do we have the right AI, BD and niche strategy to capture it?” The businesses that lead the next phase of growth will be those that recognise opportunities early and position themselves ahead of competitors.
Sources
1. Lloyds Banking Group - Business confidence rises (30 October 2026)
https://www.lloydsbankinggroup.com/media/press-releases/2026/lloyds/business-confidence-rises-economic-optimism-increases.html
2. S&P Global / services PMI report (4 November 2026)
https://www.investing.com/news/economic-indicators/uk-services-growth-hits-8month-high-in-october-pmi-shows-4997999
3. REC / KPMG - Report on Jobs, October data (9 November 2026)
https://www.rec.uk.com/our-view/news/press-releases/report-jobs-uncertainty-and-rising-costs-dampen-staff-recruitment-october2
4. UK Government - Rolls-Royce engine programme
https://www.gov.uk/government/news/government-and-rolls-royce-agree-25bn-to-build-jet-engines-in-the-uk-and-create-tens-of-thousands-of-jobs
5. UK Government - Sumitomo Electric subsea cable factory
https://www.gov.uk/government/news/national-energy-security-supported-by-new-subsea-cable-factory
6. Airbus - Broughton production expansion
https://www.airbus.com/en/newsroom/press-releases/2026-09-airbus-invests-into-uk-manufacturing-to-support-global-production-ramp-up?trk=public_post_comment-text
7. UK Government - Strategic Sites Accelerator
https://www.gov.uk/government/news/mayors-and-local-leaders-work-with-no10-north-to-drive-search-for-top-10-biggest-strategic-investment-sites-across-country
8. UK Government - Industrial Strategy skills opportunities
https://www.gov.uk/government/news/over-100000-job-and-training-opportunities-a-year-to-give-young-people-a-route-into-britains-growth-industries-as-part-of-industrial-strategy
9. ConstructUK / S&P Global - Construction PMI, October
https://constructuk.com/sp-global-uk-construction-pmi-weaker-housing-activity-weighs-on-sector-in-october/
10. National Wealth Fund - Statement on Budget and additional capitalisation (28 October 2026)
https://umbraco-prod.nationalwealthfund.org.uk/news-and-publications/news/national-wealth-fund-statement-on-budget-and-additional-capitalisation/
Stay connected with news and updates!
Join our mailing list to receive the latest news and updates from our team.
Don't worry, your information will not be shared.